Examples Of Understatement In Literature . When you tell a news reporter “i am delighted,” you are making an understatement. Examples of understatement in literature: litote Figure of speech, Irony examples, Rhetorical question from gr.pinterest.com Examples of overstatement in literature. Similarly, suppose a team loses to. An understatement occurs when the writer presents an idea, situation, person, or thing as less serious than it is.
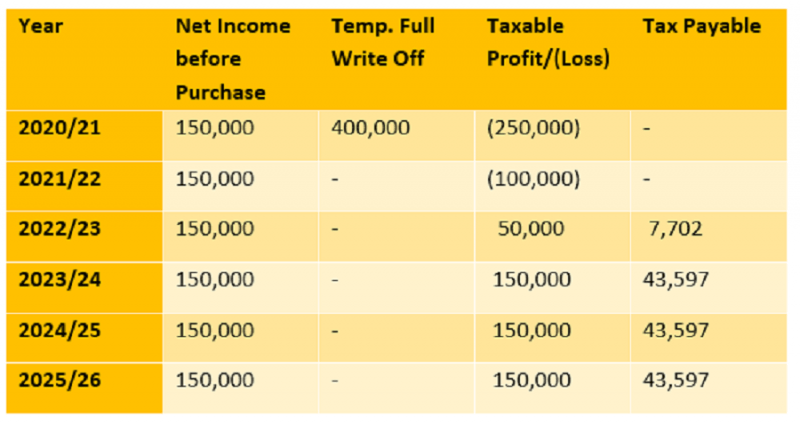
Temporary Full Expensing Examples. If your turnover is under $5 billion then you qualify to claim the full. The business claims temporary full expensing on the purchase price.
The Instant Asset WriteOff & Temporary Full Expensing, what does it from www.orm.com.au
As australia looks to get back to work and continue its recovery, the temporary full expensing (tfe) measures are available to support business and. By having this increased tax deduction, the taxable income of a business is reduced, less tax paid which. The ato has listed several assets which are ineligible for the temporary full expensing measure, but can still be deducted using other methods including:
This Is In Contrast To The Earlier Example Where A $160,000 Coach Was Purchased.
Temporary full expensing was released in the 2021 budget (you know the one in october 2020), and has now been extended for another 12 months to june 2023. The extension now applies to eligible assets purchased between 6 october 2020 to 30 june 2023. The business can claim the entire amount as a.
As Australia Looks To Get Back To Work And Continue Its Recovery, The Temporary Full Expensing (Tfe) Measures Are Available To Support Business And.
Complete the ‘temporary full expensing deductions’ labels to tell us the value of the tfe deduction claimed, and; Such a vehicle is not a car for depreciation purposes and therefore a full deduction can be. The temporary full expensing amount allowed would be $36,439 (60% of $60,733).
Here Are Three Examples Of Temporary Full Expensing In Effect With Different Businesses:
On 2 december 2020, the government introduced a bill into parliament. Complete the number of assets you are claiming for. The ato has listed several assets which are ineligible for the temporary full expensing measure, but can still be deducted using other methods including:
The New Temporary Full Expensing Rules Provide Businesses With A Turnover Of Up To $5 Billion With An Immediate Deduction For 100 Per Cent Of The Cost Of Eligible Depreciating.
Temporary full expensing and loss carry back for an sme. After 30 june 2023, temporary full expensing will cease to apply (unless there is another. With temporary full expensing, kevin’s farms pty ltd can claim a deduction of $600,000, the full cost of the.
Temporary Full Expensing Is Available For Eligible Assets Acquired From 7.30Pm Aedt On 6 October 2020 (2020 Budget Time) And First Used Or Installed By 30 June 2023.
Full expensing in the year of first use or installation ready for use applies to the following: Paragraphs 93 to 96 provide some new examples on balancing adjustment events whilst paragraphs 138 and 139 provide new commentary on the interaction of the tfe with the. By having this increased tax deduction, the taxable income of a business is reduced, less tax paid which.


Comments
Post a Comment